#TDS

17 articles

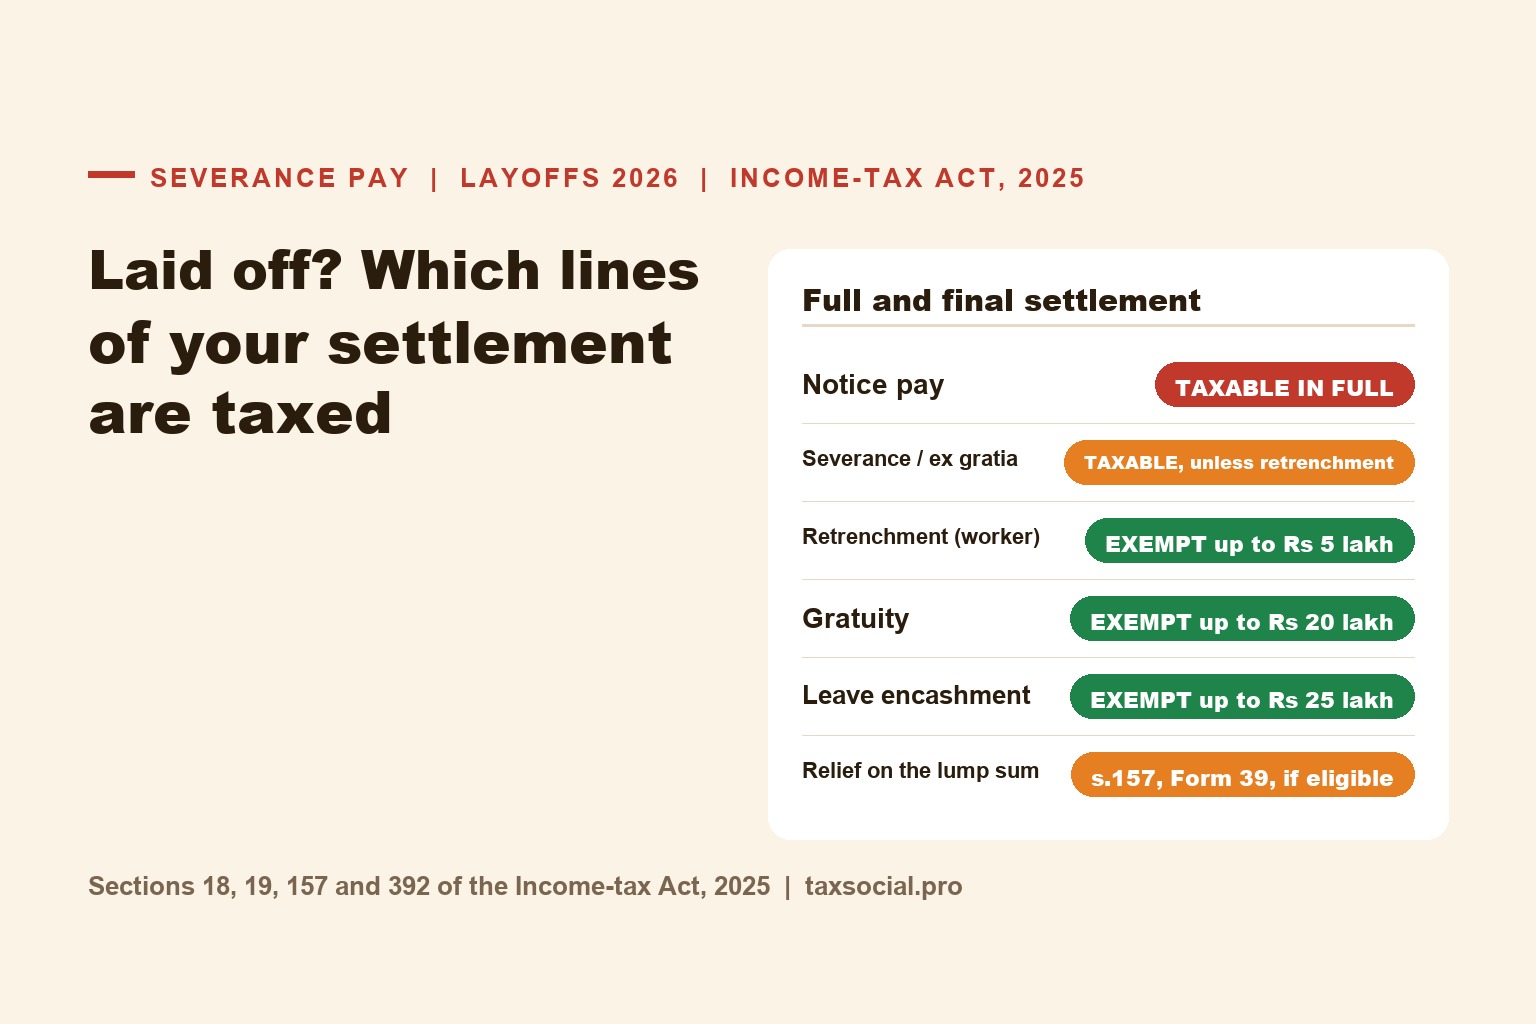
Severance Pay Tax in India (2026): Is Your Layoff Package Taxable? Notice Pay, Ex Gratia, Retrenchment Compensation, Gratuity and Leave Encashment Under the Income-tax Act, 2025

Deep Jasani
Deep Jasani · Sep 17
Laid off in 2026? Your settlement is taxed line by line under the Income-tax Act, 2025: notice pay in full; severance as profits in lieu of salary unless it is retrenchment compensation to a worker (up to Rs 5 lakh deductible); gratuity up to Rs 20 lakh; leave encashment up to Rs 25 lakh.

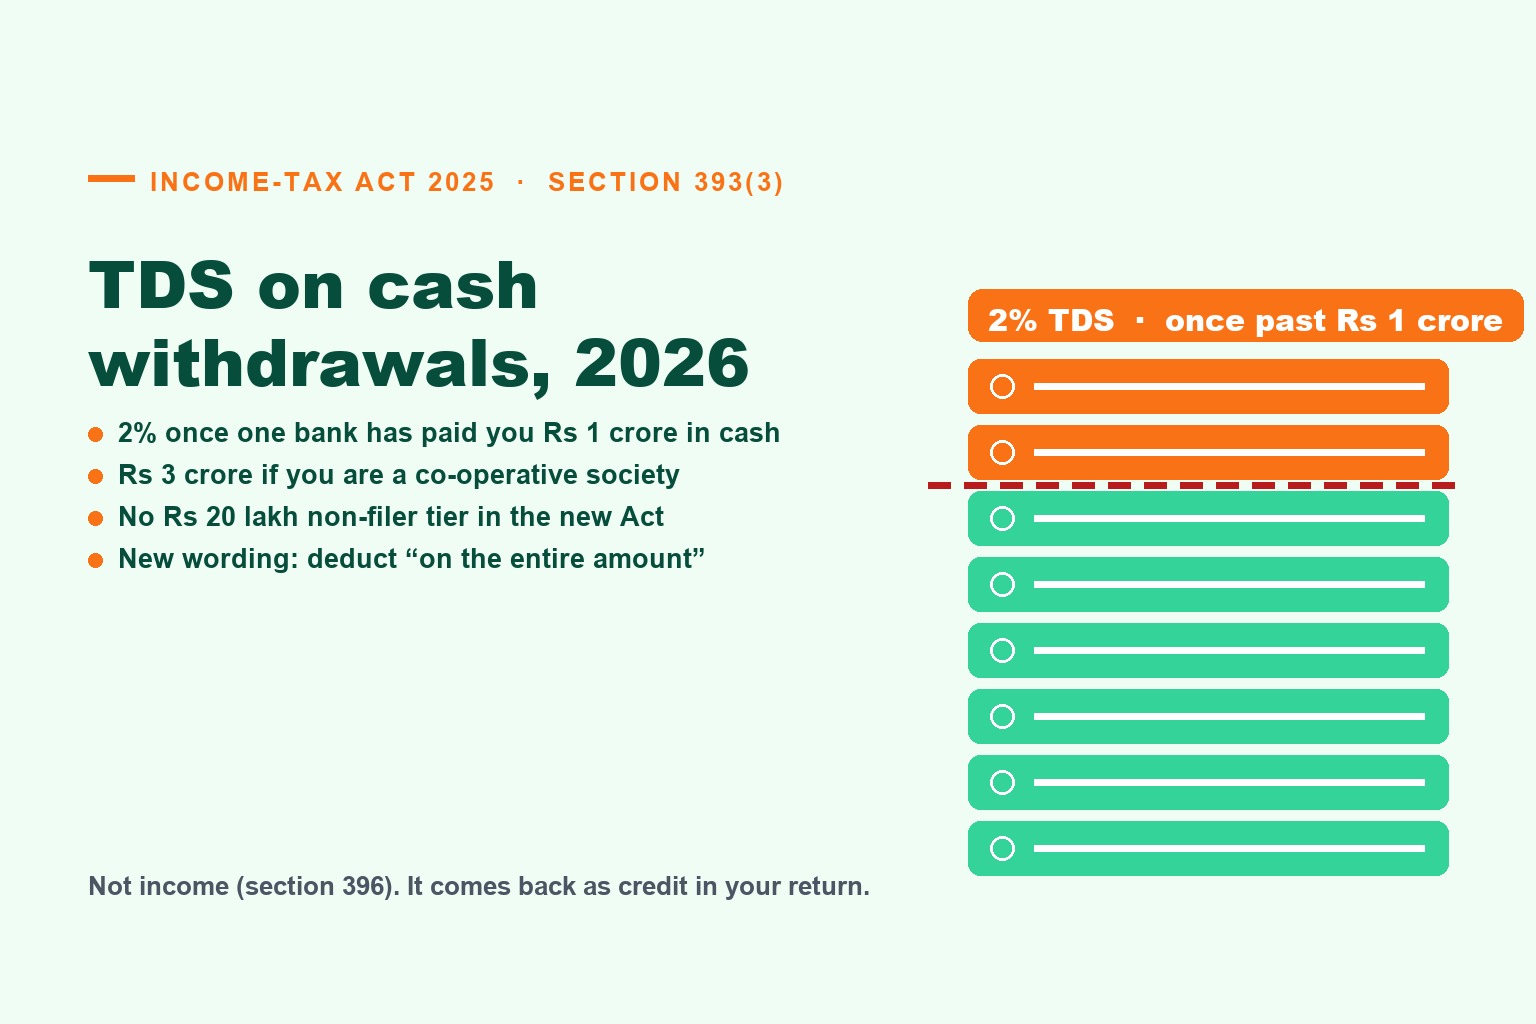
TDS on Cash Withdrawals From 1 April 2026: Section 393(3) Replaces 194N, the Rs 20 Lakh Non-Filer Tier Is Gone, and the New Text Says "Entire Amount"

Mrunmai Madaye
From 1 April 2026 the bank deducts 2% on cash withdrawals above Rs 1 crore (Rs 3 crore for a co-operative society) under section 393(3) of the Income-tax Act, 2025. Two things changed that most bank FAQs have not caught: the old non-filer tier is not in the new Act, and the new text says the deduction is "on the entire amount".

Form 146 After the 18 August Remittance Drive: What the Certificate Says, What Rule 220 Requires, and the File a Remitter Has to Hand Over

Vijay R S
Vijay R S · Sep 1
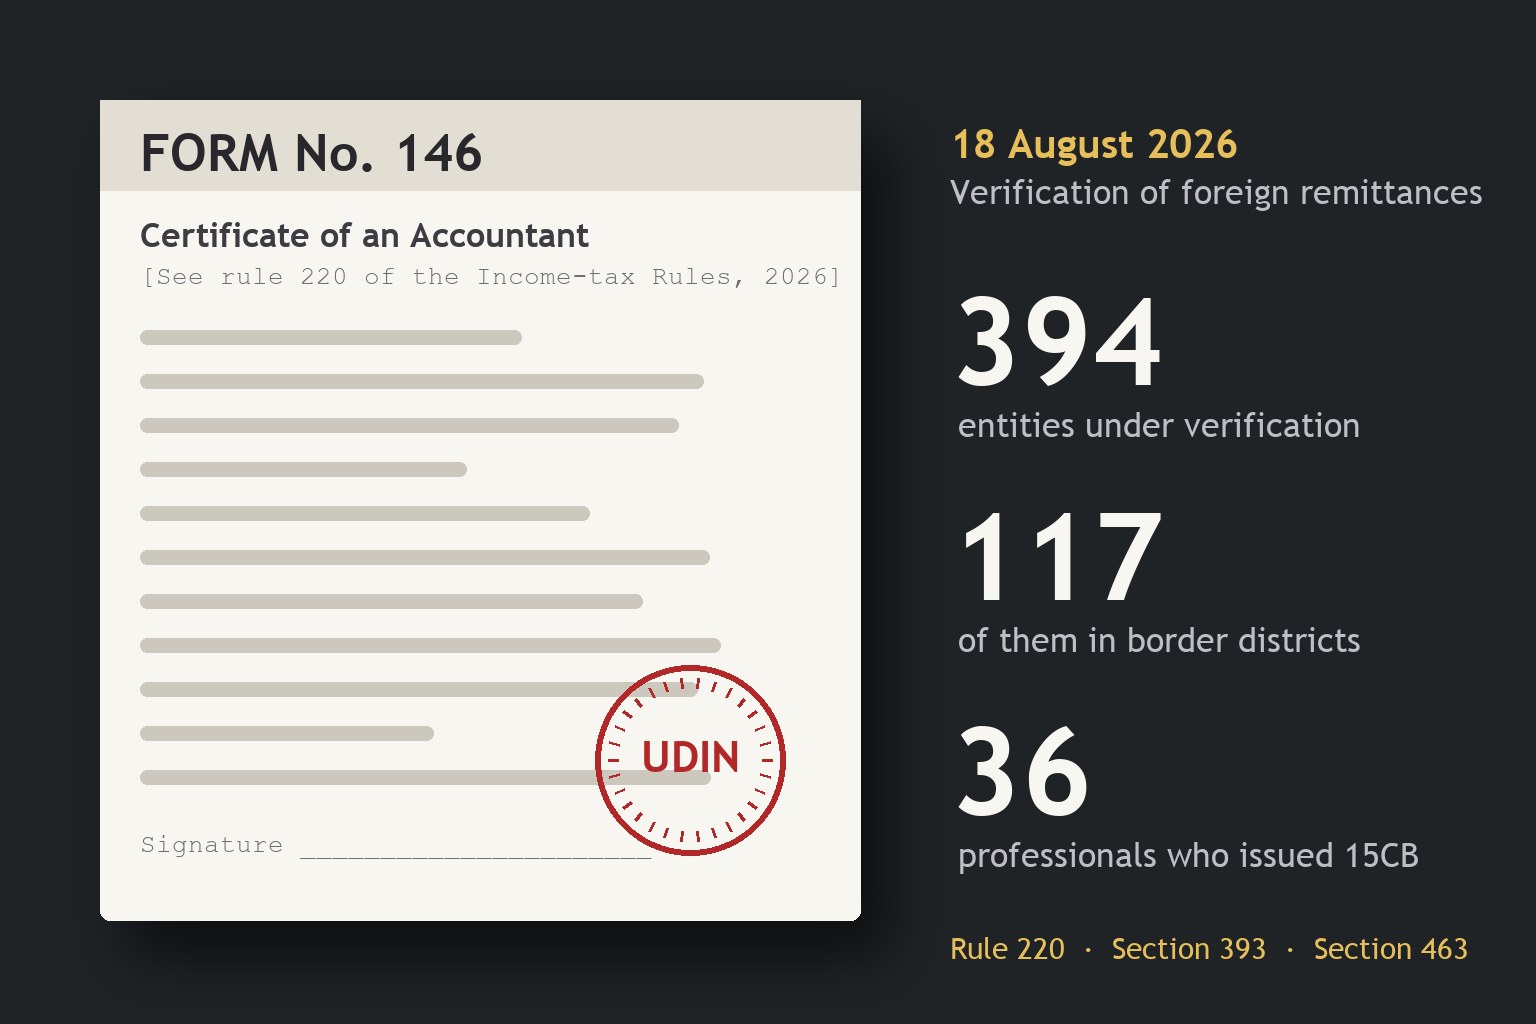
The Income Tax Department is verifying 394 remitters and 36 professionals who signed Form 15CB. The same certificate is now Form 146 under Rule 220 of the Income-tax Rules, 2026. What Rule 220 actually requires, what the accountant certifies, the section 463 and 462 penalties, and the diligence file that answers every check in the press release.

Crypto and VDA Tax in India for AY 2026-27: The 30% Flat Rate, 1% TDS, Schedule VDA in ITR, and the New Section 509 Reporting Regime from 1 April 2026

TaxSocial Editorial Team
Crypto and NFT gains are taxed at a flat 30% under Section 115BBH (Section 194 of IT Act 2025) — only cost of acquisition deductible, no loss set-off, no carry-forward. 1% TDS under 194S. Disclose in Schedule VDA. From 1 April 2026: exchanges report under Section 509; penalties under Section 446.

TDS on Sale of Property in India: Resident vs NRI Seller, Section 393(1) and 393(2) Mechanics Under the Income-tax Act, 2025

TaxSocial Editorial Team
TDS on property sale under the Income-tax Act, 2025: resident seller 1% TDS under Section 393(1) [Sl. 3(i)] above Rs 50 lakh; NRI seller TDS under Section 393(2) [Sl. 17] — no threshold, 12.5% LTCG / slab STCG plus surcharge. Form 141 replaces Form 26QB; Section 395 / Form 128 lower-TDS.

The Quiet TDS Trap in the 1 April 2026 Transition: How the "Earlier of Credit or Payment" Test Decides Whether You Cite the 1961 Act or Section 393

TaxSocial Editorial Team
The 1 April 2026 cutover to the Income-tax Act, 2025 hides a quiet TDS trap. Deduction events whose earlier-of-credit-or-payment date falls on or before 31 March 2026 stay under the 1961 Act (old section codes, Form 26Q/27Q), even if deposited in April. Later events move to Section 393.

Help

Need help? Browse our Help Center for guides on using TaxSocial.

Visit Help Center

View Plans