#AY 2026-27

25 articles

Income Tax Refund Delayed for AY 2026-27? How Many Days a Refund Takes, How to Check the Status, the Eight Reasons It Is Stuck, and the Interest You Are Owed

Najma K
Najma K · Sep 17
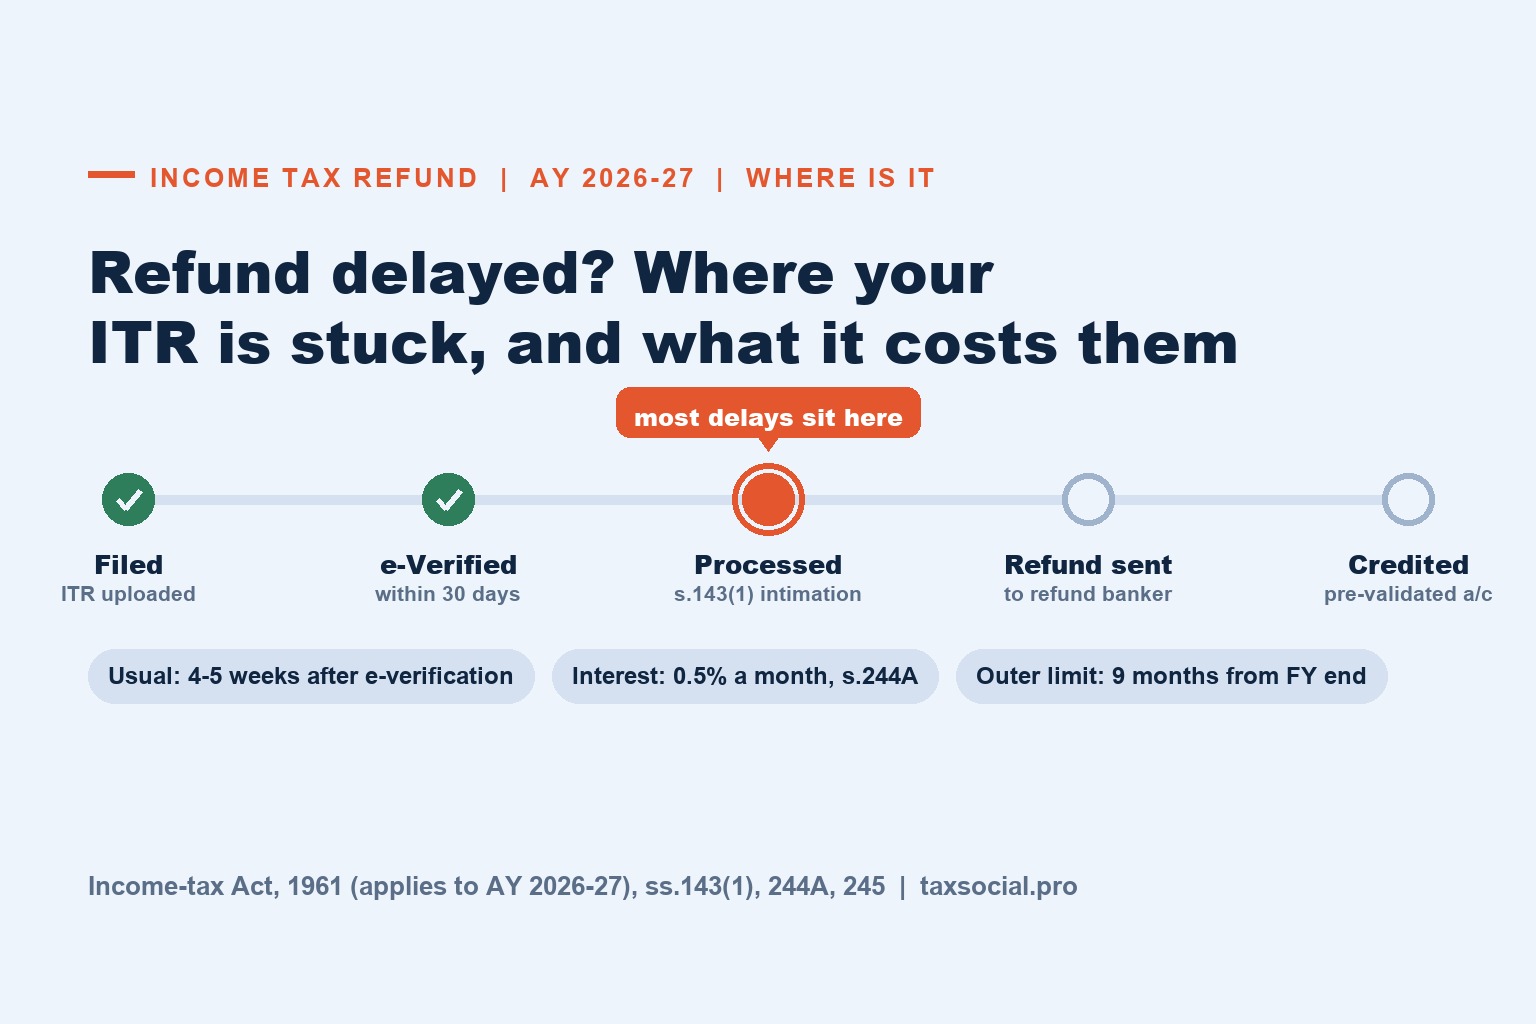
A refund for AY 2026-27 usually lands four to five weeks after e-verification; the legal outer limit is nine months from the end of the financial year the return was filed in. How to read the portal status, the eight reasons a refund stalls, and the 0.5% a month interest under Section 244A.

Form 3CD Clause 44 (GST Break-up of Expenditure): Why Your CA Is Asking for Every Supplier's GST Number

Sachin Mohite
Sachin Mohite · Sep 11
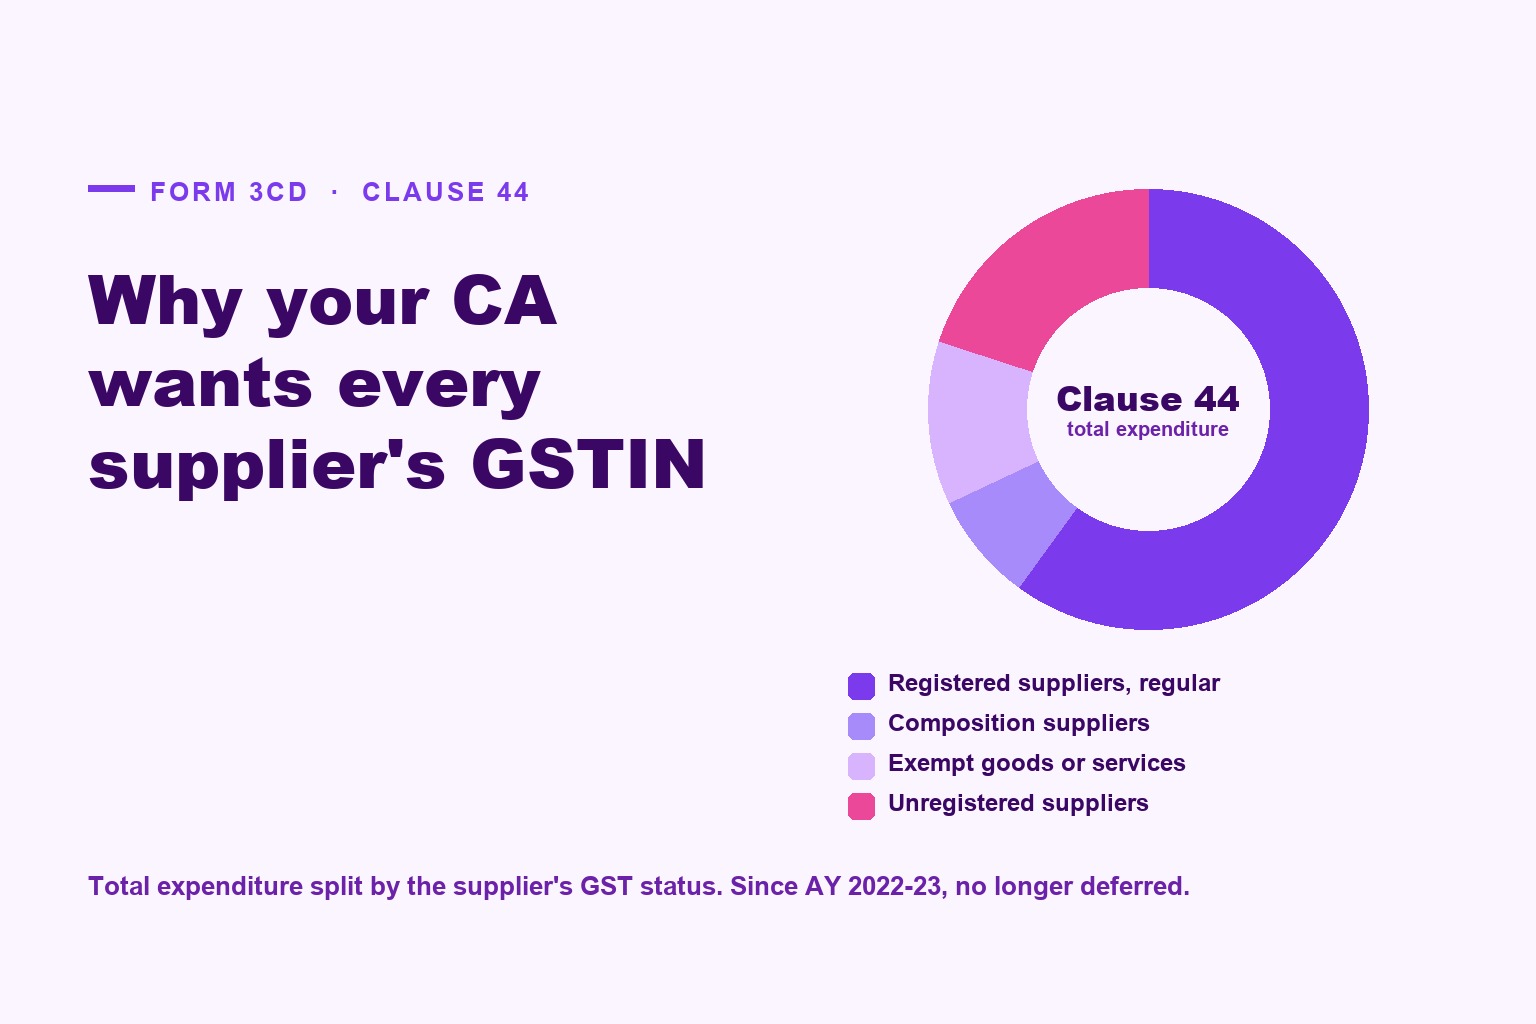
Clause 44 of Form 3CD makes the tax auditor split your total expenditure by the supplier's GST status: exempt goods or services, composition dealers, other registered suppliers, and unregistered suppliers. It was deferred four times and has been live since AY 2022-23. What the columns mean, what is excluded, how to build the data from GSTR-2B and the purchase register, and why the number has to tie to your GST returns.

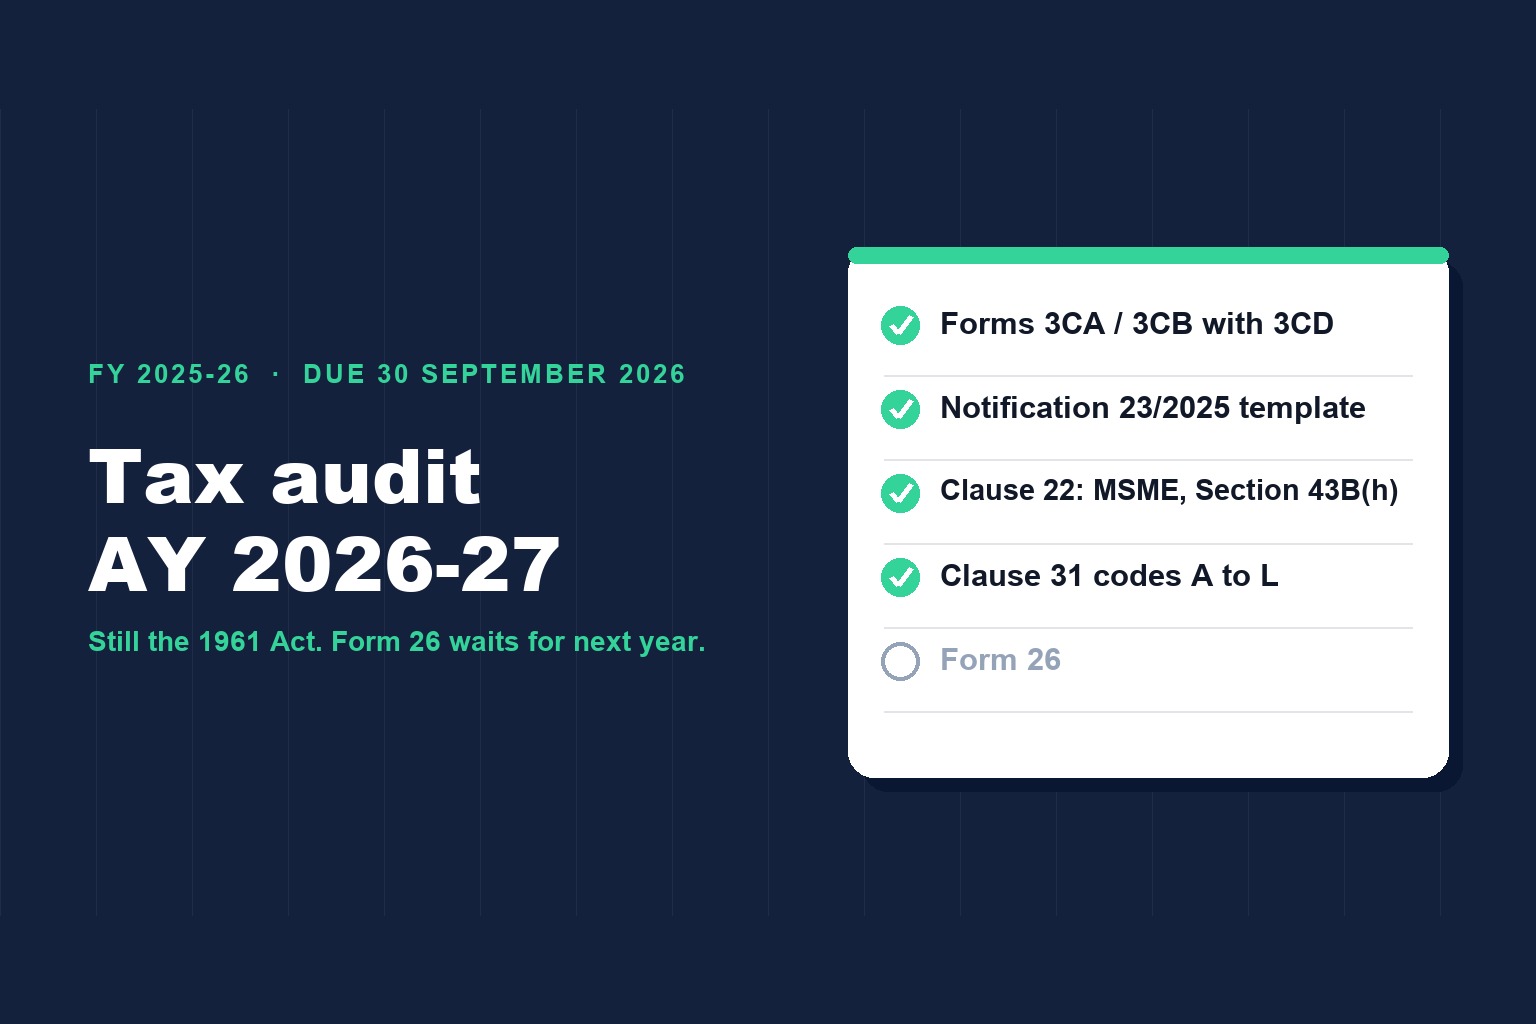
Documents Your CA Needs for the Tax Audit: The 15-Item Checklist for AY 2026-27 (and Which Form 3CD Clause Each One Feeds)

Harsh Vyas
Harsh Vyas CA · Sep 11
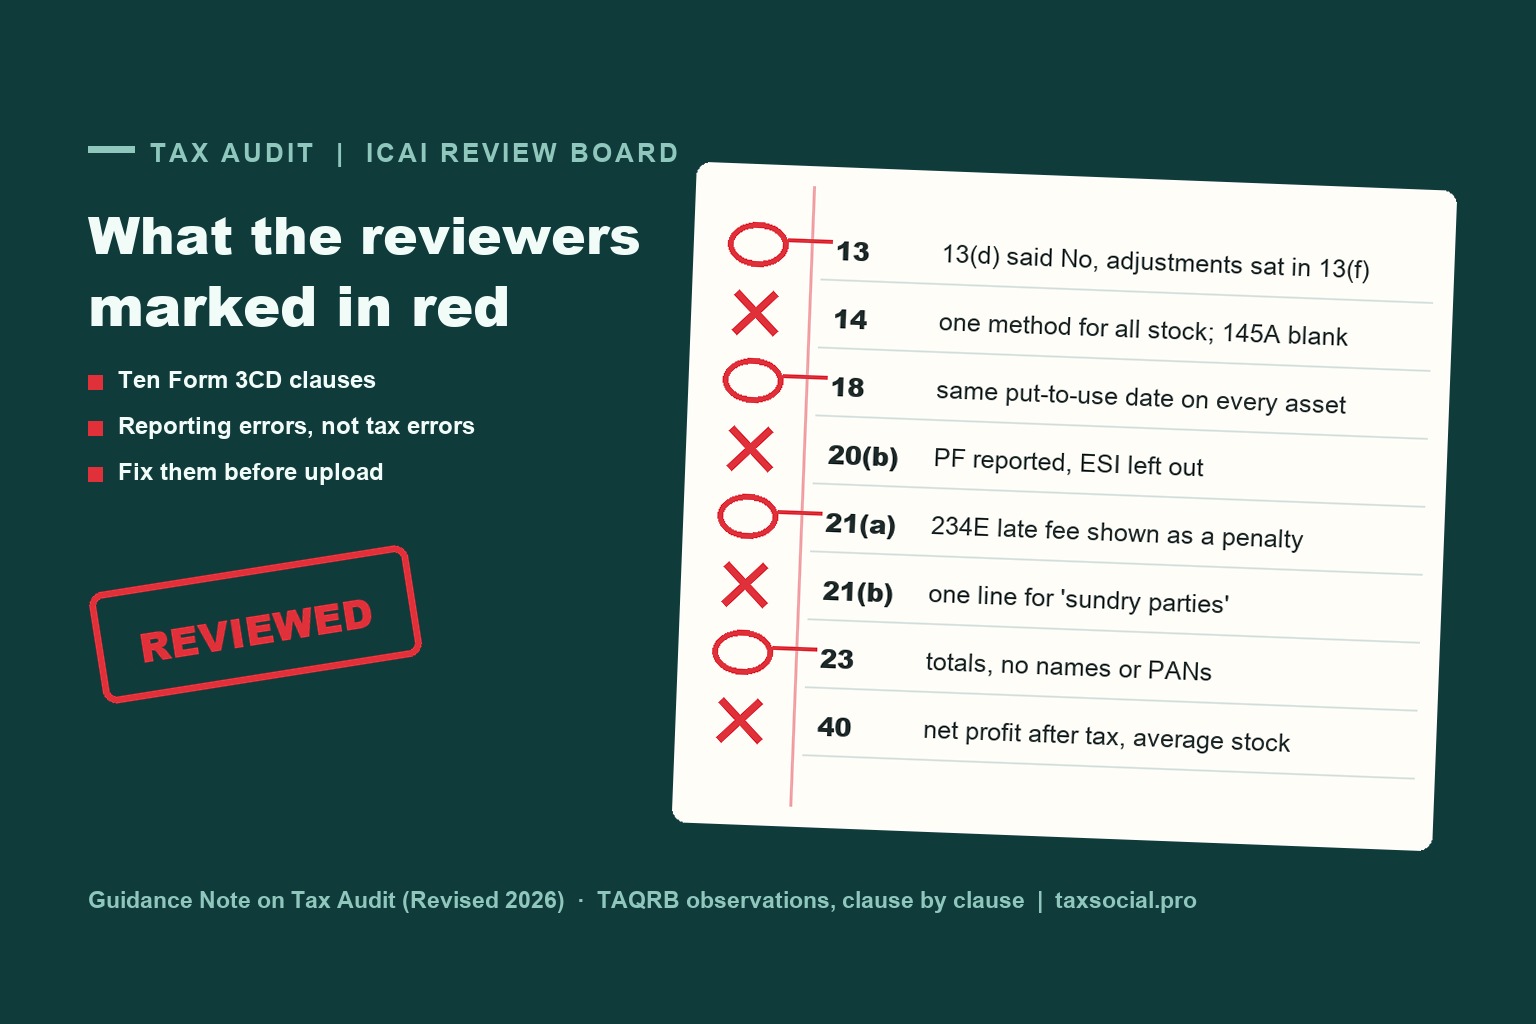
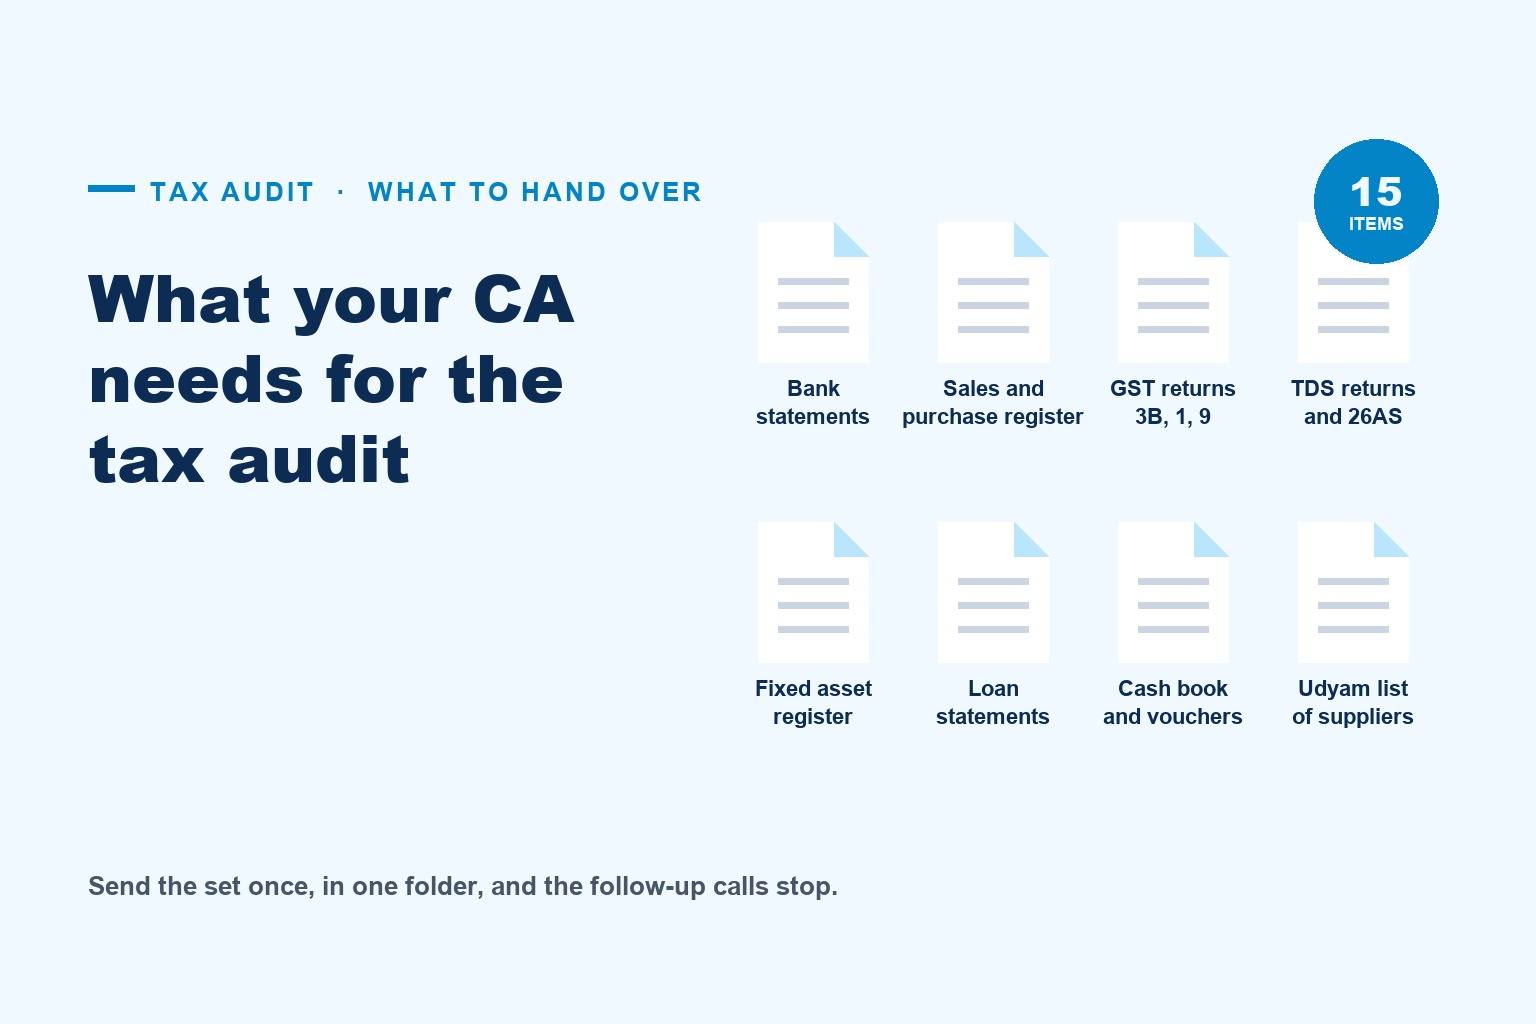
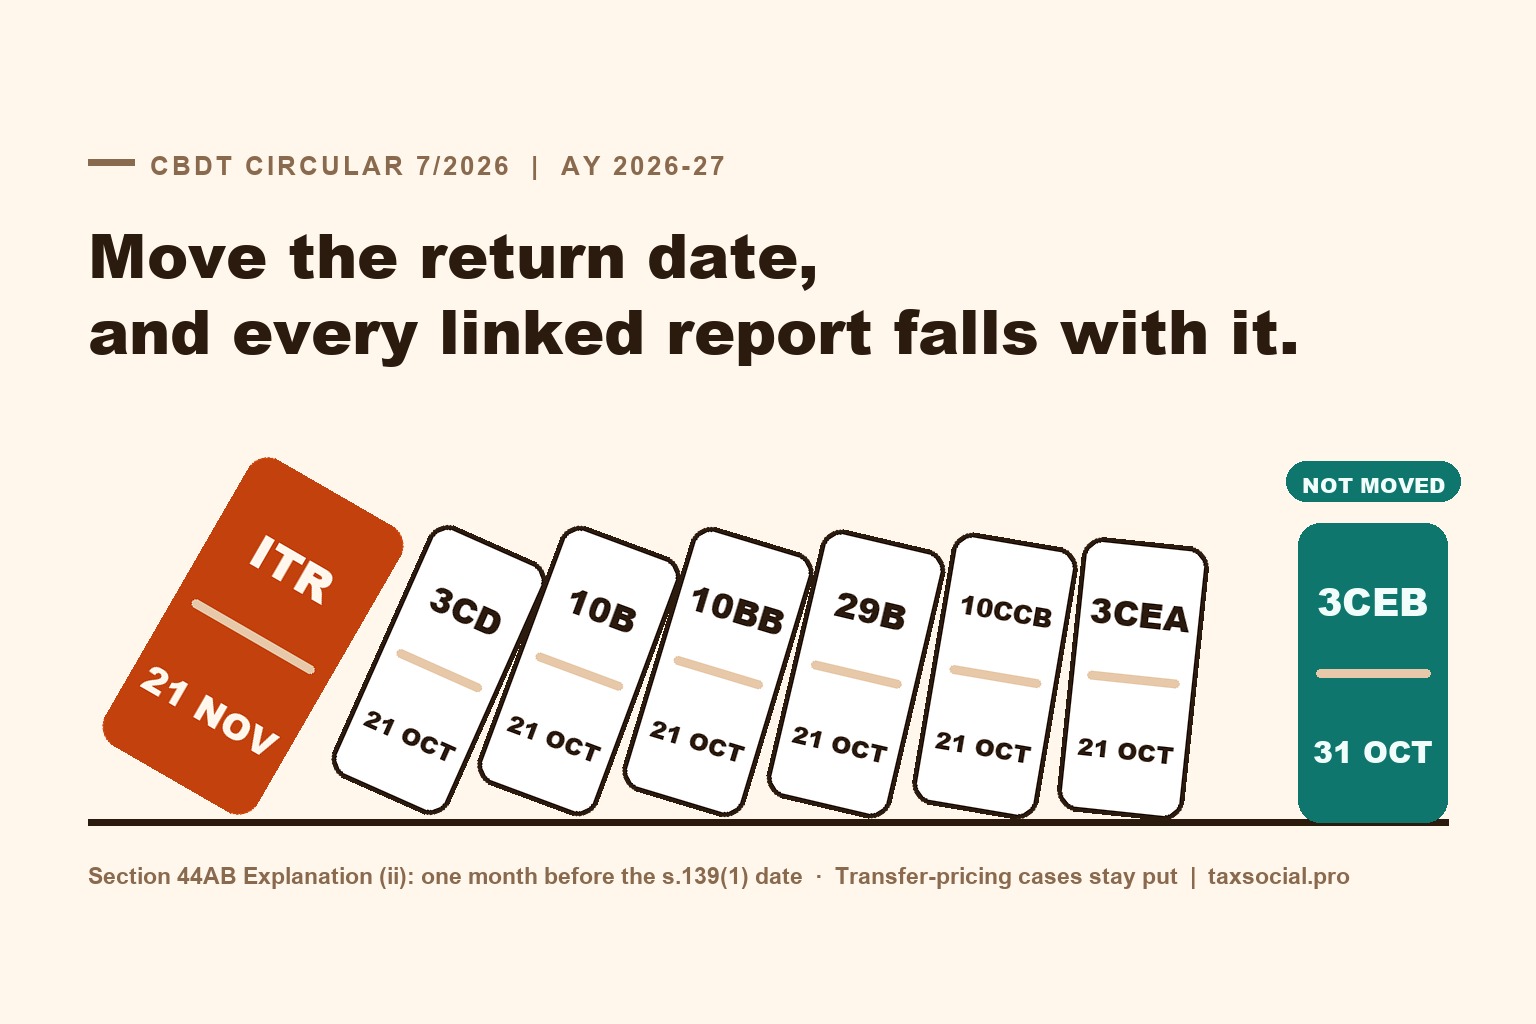
The tax audit report for AY 2026-27 is due 21 October 2026 (extended). Here is the list a tax auditor needs from a client, in one folder: books and bank statements, GST and TDS returns, the fixed-asset and loan registers, the cash-transaction schedule, the MSME supplier list, the supplier GSTIN master for clause 44, and eight more, each tied to the Form 3CD clause it answers.

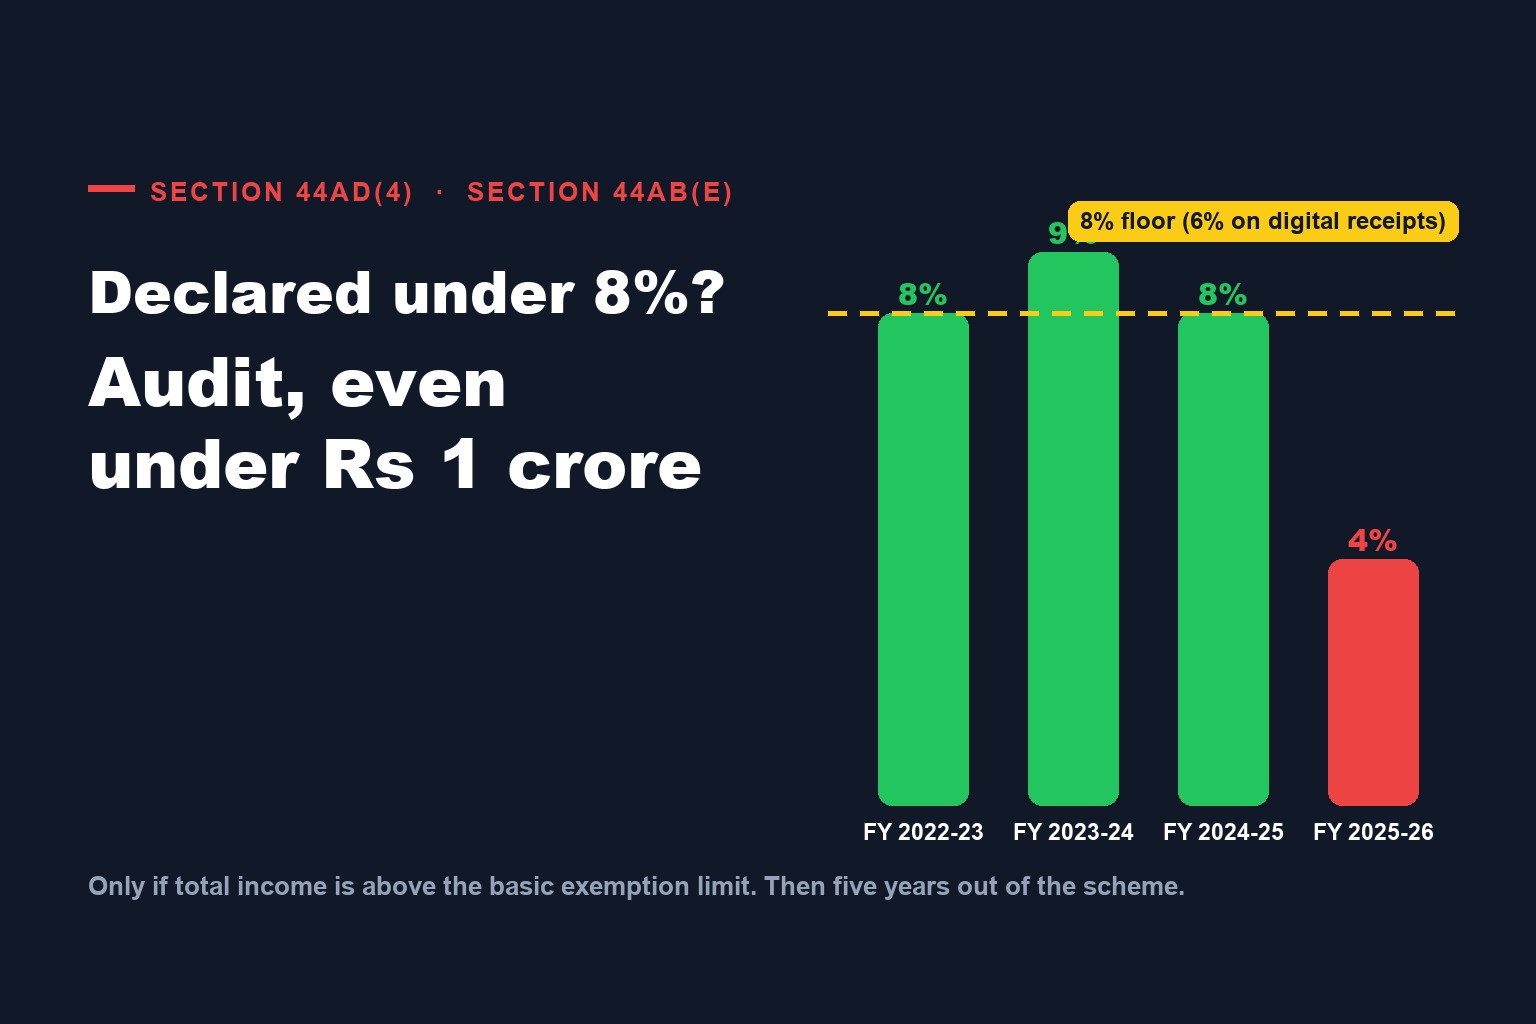
Declared Profit Below 8% or 6%? You May Need a Tax Audit Even Under Rs 1 Crore: The Section 44AD(4) Trap, and Who It Does Not Catch

Vijay R S
Vijay R S · Sep 11
Turnover under Rs 1 crore does not settle the tax-audit question. If you used Section 44AD in any of the last five years and now declare below 8% (6% on digital receipts), Section 44AD(4) applies, and Section 44AB(e) requires an audit when your total income exceeds the basic exemption limit (Rs 4 lakh, new regime). A first-time low-profit declarant who never opted in is NOT caught.

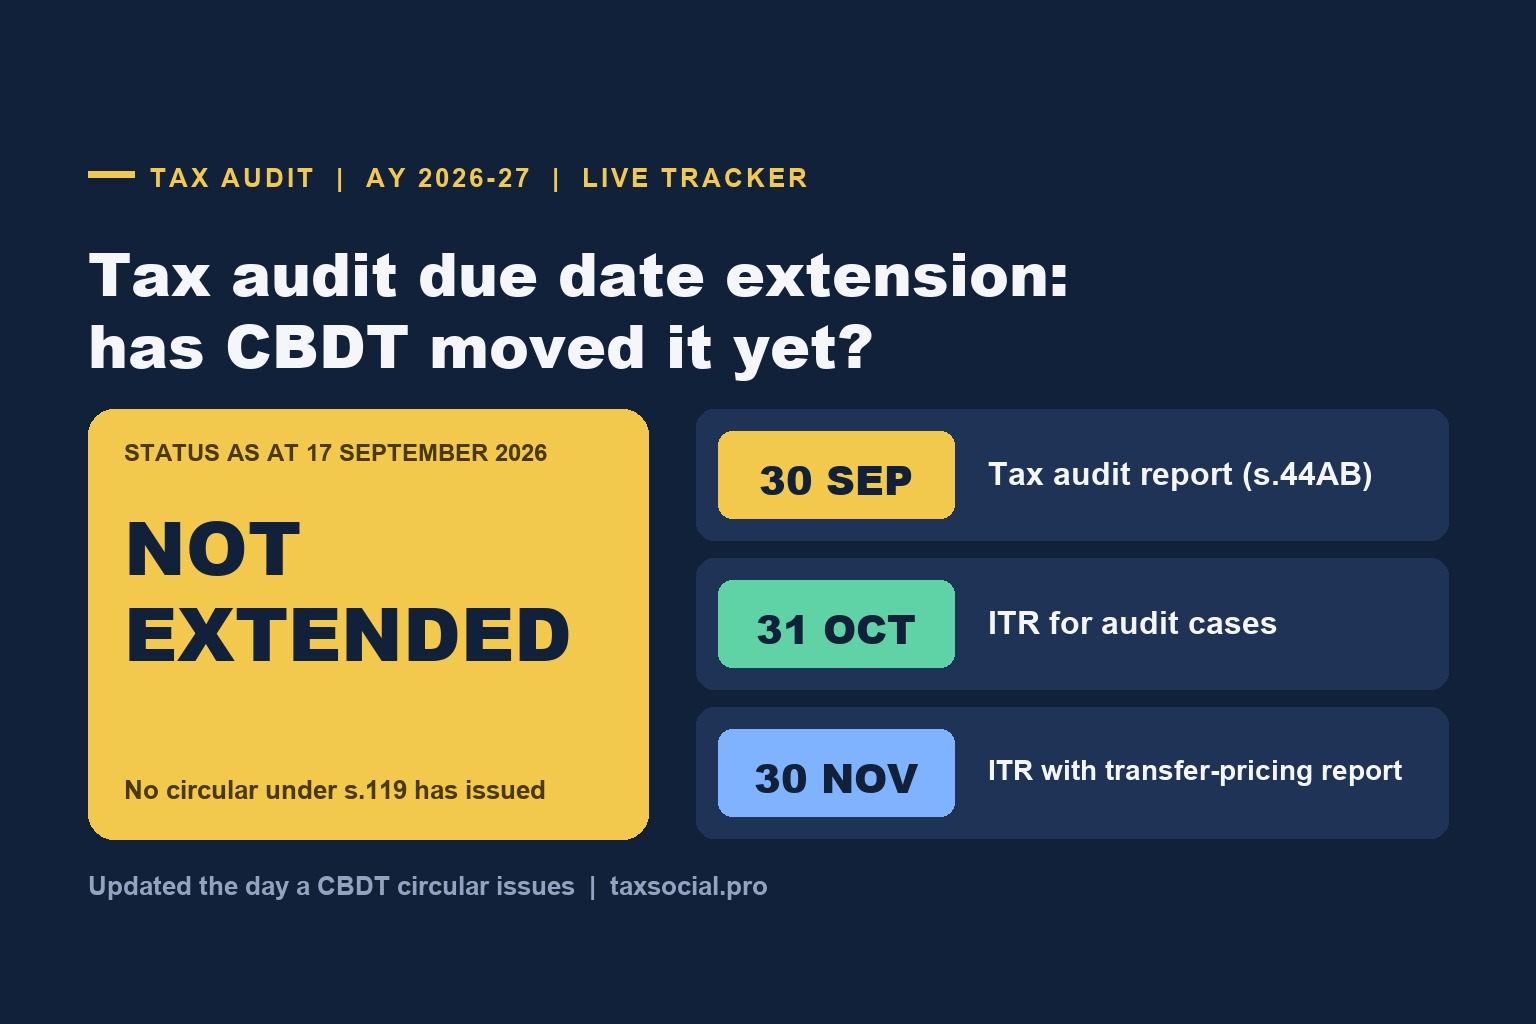
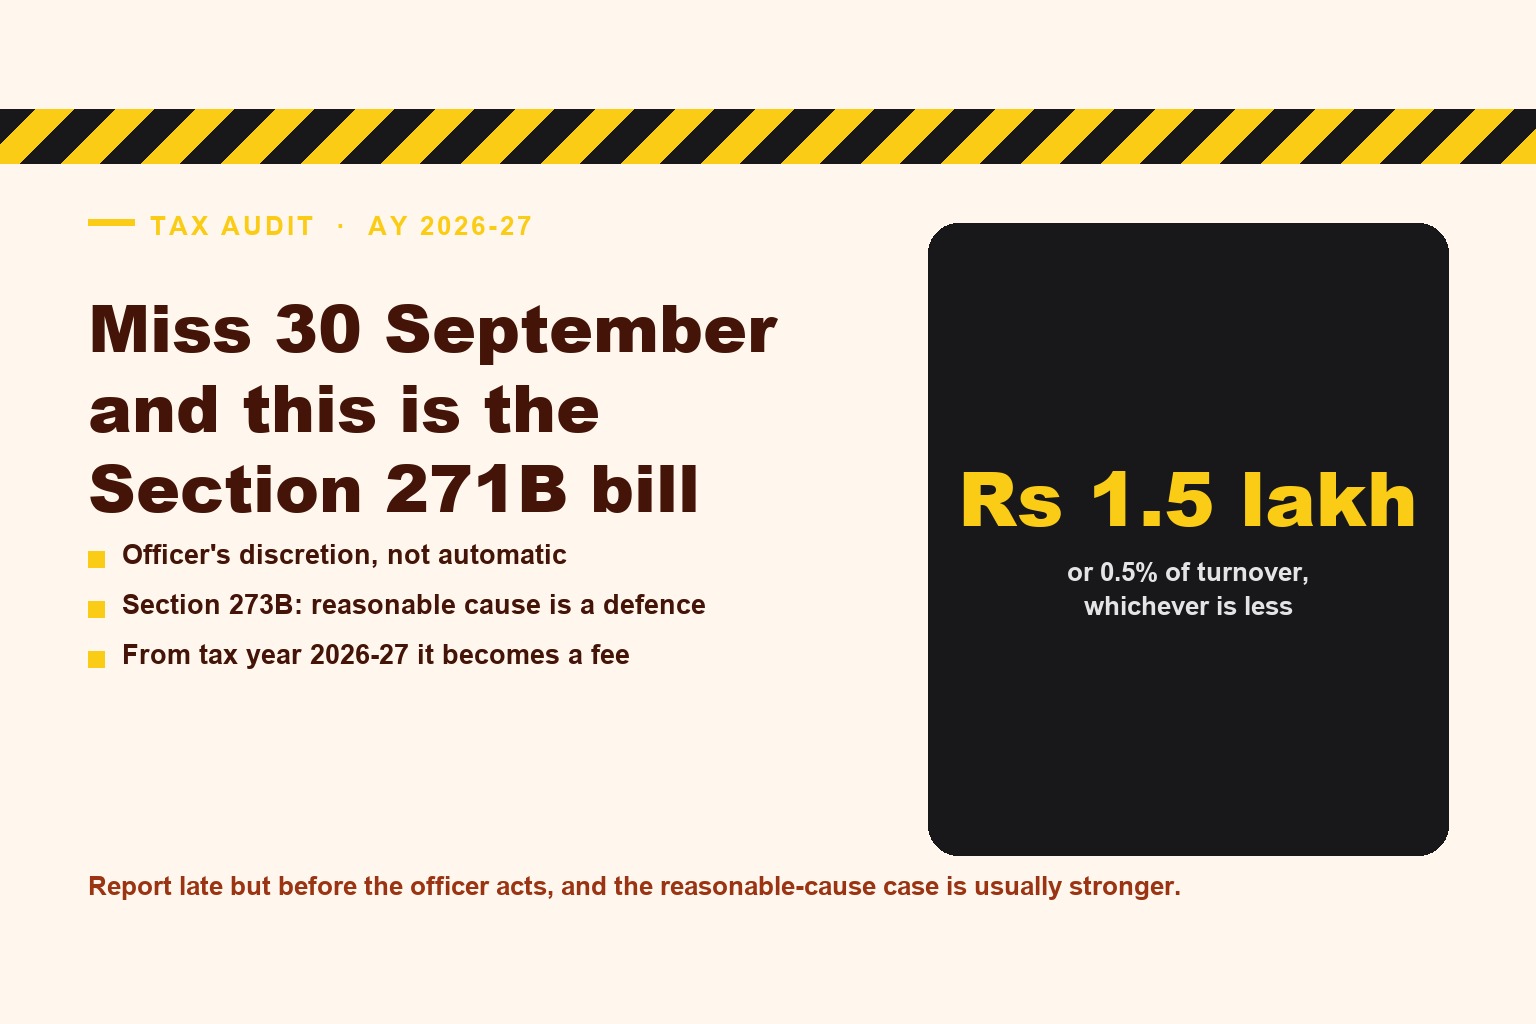
Tax Audit Due Date 21 October 2026 (Extended From 30 September): The Section 271B Penalty If You Miss It (0.5% of Turnover, up to Rs 1.5 Lakh), and the Fee That Replaces It Next Year

Vijay R S
Vijay R S · Sep 11
Miss the tax-audit date for AY 2026-27 (now 21 October 2026, extended from 30 September) and Section 271B lets the Assessing Officer levy 0.5% of turnover or gross receipts, capped at Rs 1.5 lakh. It is discretionary, and Section 273B waives it for reasonable cause. From tax year 2026-27 the Income-tax Act, 2025 replaces it with a fixed fee: Rs 75,000 for up to a month, Rs 1.5 lakh after.

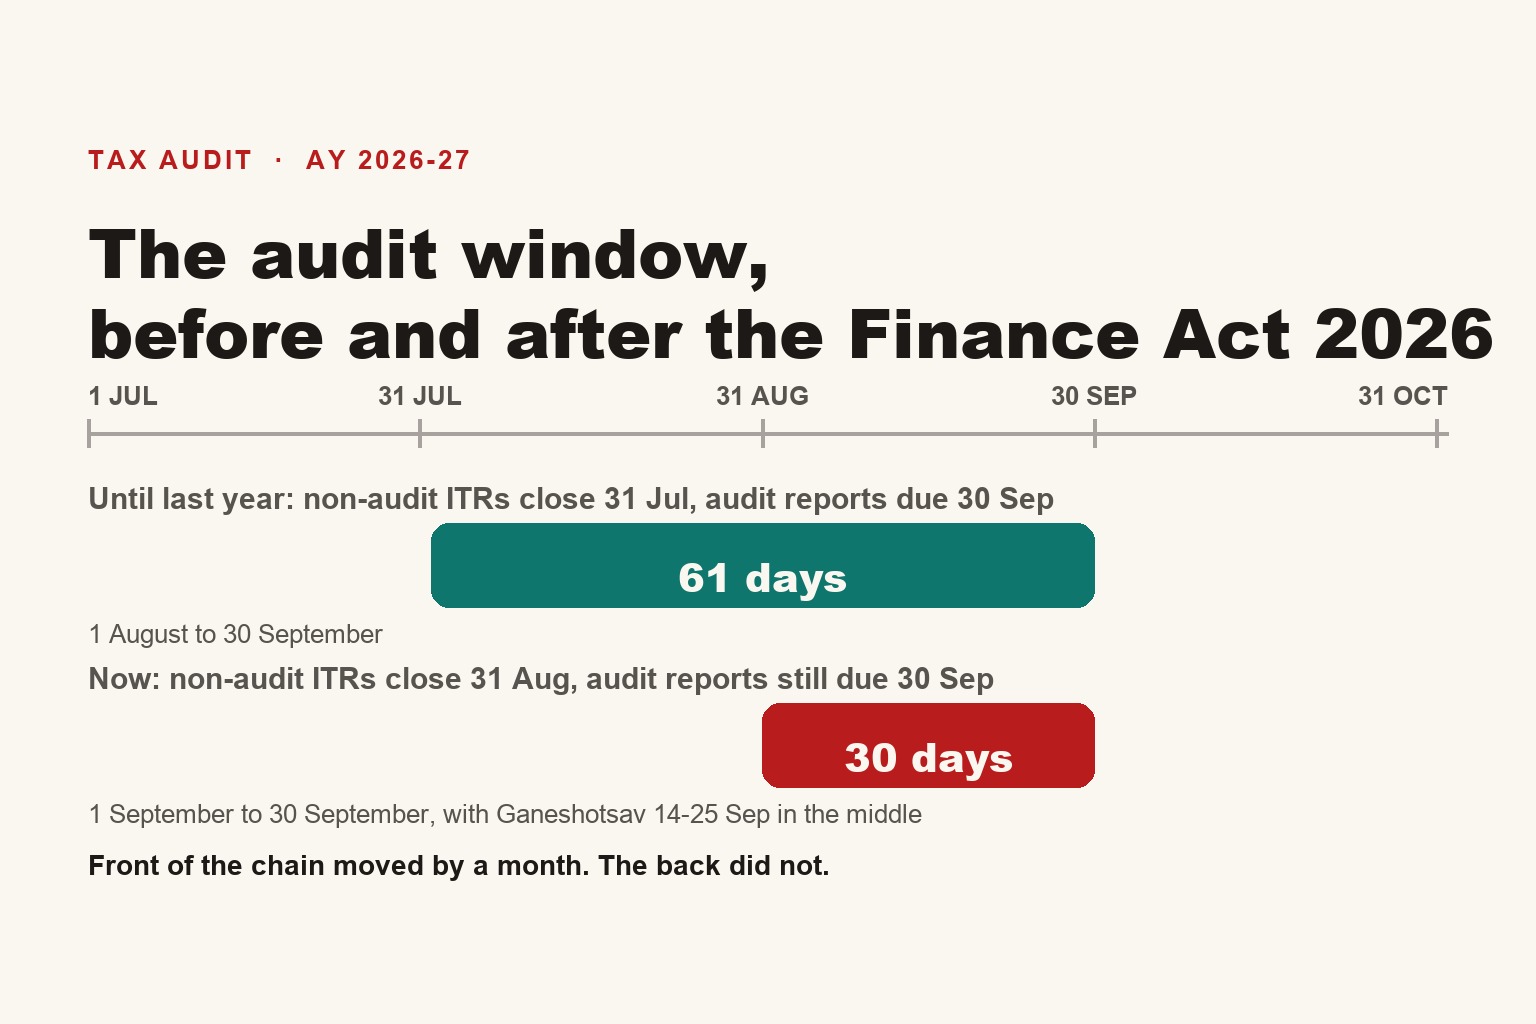
The Finance Act 2026 Cut the Tax Audit Window From 61 Days to 30: Why 30 September Must Move to 31 October, and How to Fix the Law

Harsh Vyas
Harsh Vyas CA · Sep 7
The Finance Act 2026 moved the non-audit business ITR date to 31 August but left the tax audit report at 30 September. The working audit window fell from 61 to 30 days. The September calendar, what CBDT did in 2024 and 2025, and a two-part fix: extend to 31 October now, then re-link the law.

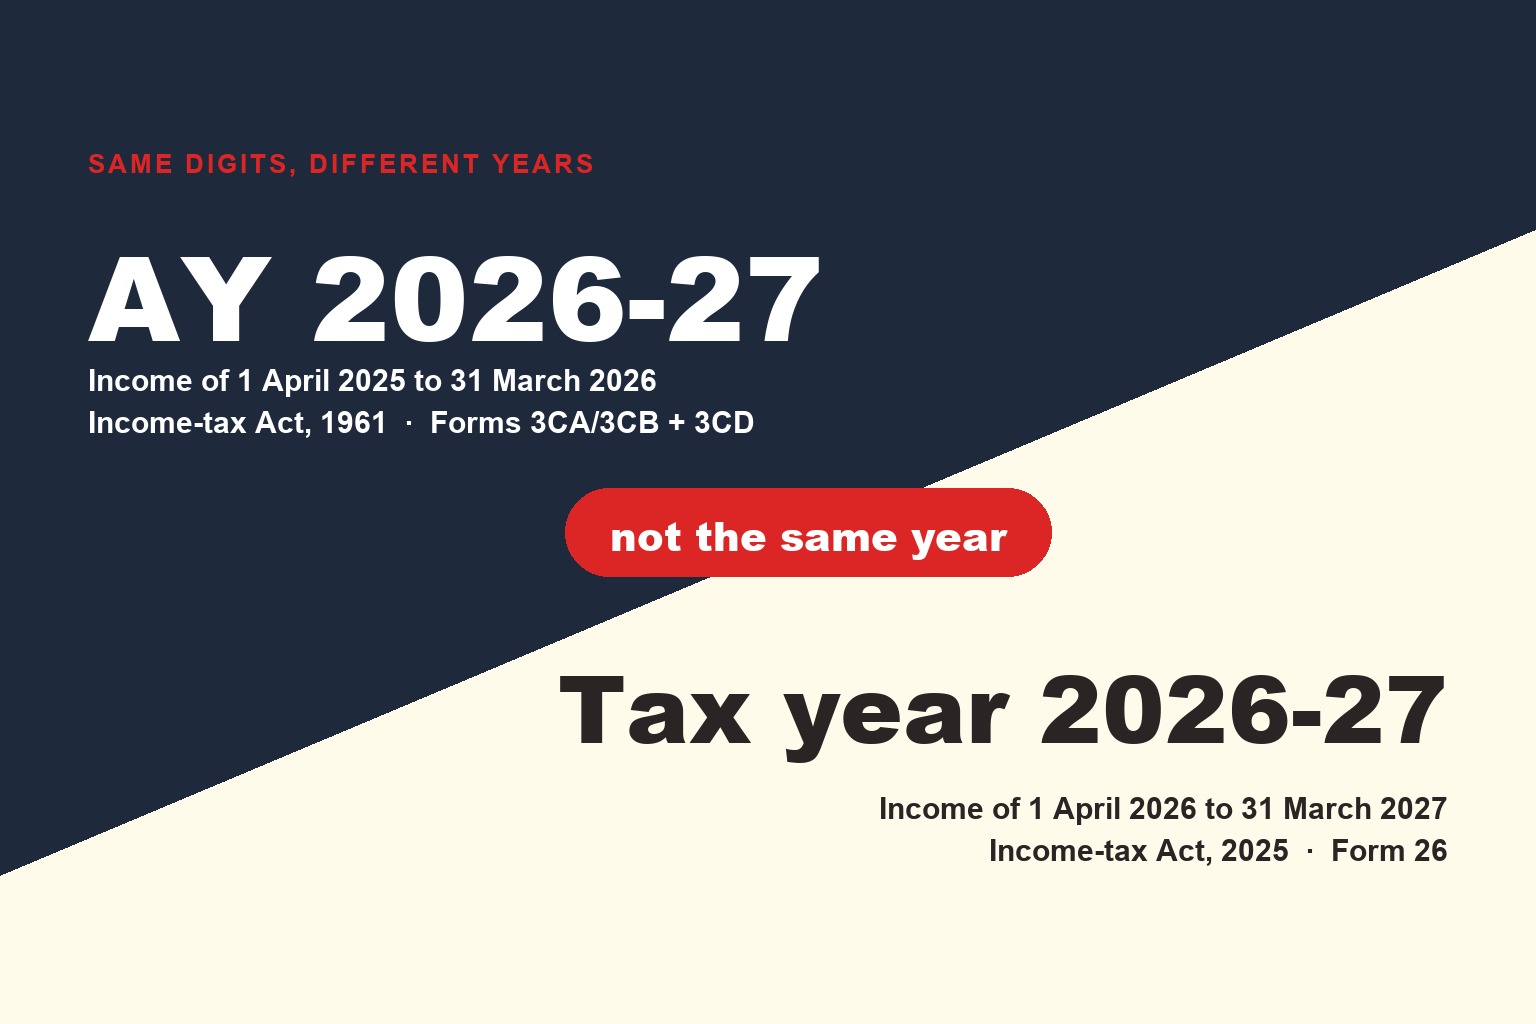
Tax Year vs Assessment Year vs Previous Year — What Changed on 1 April 2026 Under the Income Tax Act, 2025 (and What It Means for Your AY 2026-27 ITR)

TaxSocial Editorial Team
Income-tax Act, 2025 came into force 1 April 2026 — 'Previous Year / Assessment Year' replaced by a single 'Tax Year'. But your AY 2026-27 ITR (FY 2025-26 income), filed by 31 July 2026, is still under the 1961 Act. Tax Year first applies from FY 2026-27. Full transition map inside.

Help

Need help? Browse our Help Center for guides on using TaxSocial.

Visit Help Center

View Plans